Market Volatility and Superannuation Decisions
The recent volatility in financial markets, driven by tensions involving Donald Trump’s actions towards Iran, has led to a significant number of superannuation fund members opting to move their investments into cash. This shift is particularly notable among older Australians who are nearing retirement, as they tend to be more sensitive to market fluctuations.
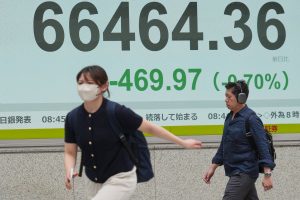
Financial experts and super funds have pointed out that while it’s natural for older Australians to worry about losing a substantial portion of their retirement savings, making impulsive decisions such as selling off shares can be detrimental. The global stock markets experienced a sharp decline in March due to the conflict, rising oil prices, and concerns about a potential recession. Australian shares dropped by 9% over the first three weeks of the month, with US shares down approximately 8%, European shares falling 9.6%, and Japanese shares dropping as much as 13%.
However, the market rebound was equally impressive, with Australian shares increasing by 7% within just over two weeks. This means that individuals who moved $100,000 from shares to cash during the last week of March missed out on a $7,000 recovery.
Super Switching Trends
According to AustralianSuper, the majority of those switching to cash were Australians over the age of 55, with 500 members per day making the switch during March, which is about four times the usual rate. Hesta, another super fund, also observed increased activity in switching between investment options.
Debby Blakey, CEO of Hesta, emphasized that knee-jerk reactions to short-term market movements could lead to irreversible losses. She advised members to seek personalized advice that considers their individual circumstances and proximity to retirement. “History shows that staying invested through market ups and downs typically delivers stronger long-term returns,” she said.
Despite the recent announcement of a two-week ceasefire between the US and Iran, the possibility of renewed hostilities remains. David Bassanese, chief economist at BetaShares, highlighted the growing concern about stagflation, characterized by higher inflation and weaker economic growth, linked to the surge in oil prices.
Long-Term Investment Strategies
Bassanese noted that the US initially expected a swift victory and possible regime change but did not anticipate Iranian resistance or the effective blockade of the Strait of Hormuz. As a result, President Trump is seeking a face-saving exit from the situation.
Regardless of the outcome of the conflict, market volatility is expected to persist. Older Australians are being encouraged to develop strategies to navigate future financial uncertainties.
AustralianSuper reported that the highest number of switches to cash occurred among members aged 55 and over, with a slight increase among those aged 40-55 and relatively stable switching among those under 40. Alistair Barker, head of asset allocation at AustralianSuper, explained that individuals over 55 often feel that every decision carries more immediate consequences.
“They’re naturally thinking not just about growth, but about how to preserve what they’ve built over time,” he said. “Your super can continue working for you even once you pass retirement, and many people still have 10, 15, or even 20 years or more of investing ahead.”
Retirees often experience anxiety due to the absence of a regular income, which makes them more vulnerable to market downturns. Barker recommended that older Australians focus on the long term, remain calm, and consult professional advisers.
Managing Sequencing Risk
Sequencing risk, which refers to the danger of poor returns early in retirement damaging wealth significantly, can be mitigated through careful planning. Darren James, director of MBA Financial Strategists, suggested that retirees should keep a portion of their pension payments in cash to cover short-term expenses.
“You’re drawing down on that regardless of what happens with markets, and it doesn’t bother you because you are drawing your income from the cash component,” he said. “You need to plan for the worst and get advice to structure things properly.”
Theo Marinis, a financial strategist, mentioned that his clients often keep two years’ worth of pension payments in cash, complemented by income from other investments. “If it’s correctly structured, there’s no need to panic,” he said. “Nobody’s got a crystal ball, so the trick is not to go all in or all out, but to remain invested appropriately for your risk profile and stage in life.”