ASX Stocks Facing Analyst Downgrades Despite Recent Reporting Season
The Australian Securities Exchange (ASX) has recently seen a clear divide emerge following the latest reporting season. While some companies, particularly established defensive players like the major banks and resource giants, continue to attract investor confidence, a closer look at analyst ratings reveals a different story for others. Several prominent ASX 200 companies, spanning the banking and energy sectors, have recently experienced downgrades to ‘Sell’ equivalent ratings from market analysts. This suggests that while investors may be seeking perceived safety, brokers are adopting a more cautious stance, scrutinising valuations and future prospects more stringently.
Here are three notable ASX 200 stocks that have recently been subject to downgrades:
Westpac Banking Corporation (ASX: WBC)
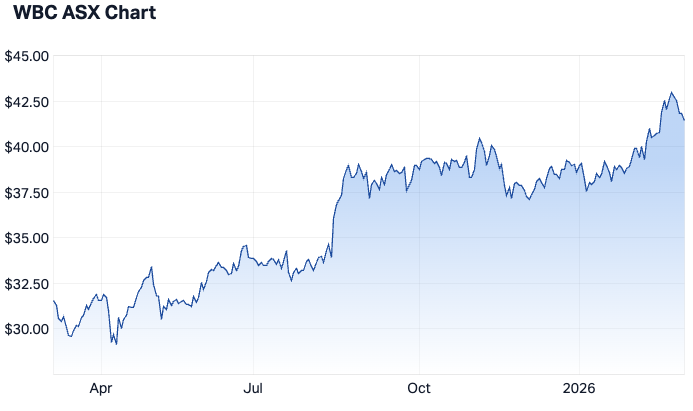
JPMorgan has recently revised its rating for Westpac Banking Corporation (ASX: WBC) from ‘Neutral’ to ‘Underweight’. This move comes despite a generally positive reporting season for the “Big Four” banks, all of which managed to exceed market expectations. Westpac, in particular, demonstrated a 5% reduction in costs and an increase in earnings estimates, even while delivering what JPMorgan characterised as the weakest relative result among the four.
Despite the solid underlying performance and the inherent defensive appeal of the banking sector, which continues to draw investor attention, analysts are increasingly concerned about stretched valuations. JPMorgan’s downgrade for WBC, while accompanied by a slight upward revision of its price target from $37.10 to $37.50, still signals a potential downside of approximately 10%. This places JPMorgan in agreement with other major brokers like Macquarie and Morgan Stanley, who also recommend an ‘underweight’ or equivalent rating for the bank.
According to Market Index’s Broker Consensus tool, Westpac is currently rated as a ‘Strong Sell’. The consensus among tracked brokers indicates a price target of $37.44, suggesting a potential downside of around 9%. This is based on two ‘Hold’ ratings and three ‘Sell’ ratings from the brokers surveyed.
Woodside Energy Group (ASX: WDS)
Ord Minnett has downgraded Woodside Energy Group (ASX: WDS) from a ‘Hold’ to a ‘Lighten’ rating. The company’s recent results highlighted a beat to net profit and an increased dividend, which would typically be viewed favourably. However, Ord Minnett’s decision to downgrade stems from ongoing uncertainty surrounding the search for a new Chief Executive Officer (CEO) and scepticism regarding Woodside’s capacity to supplement its dividend yield through its balance sheet.
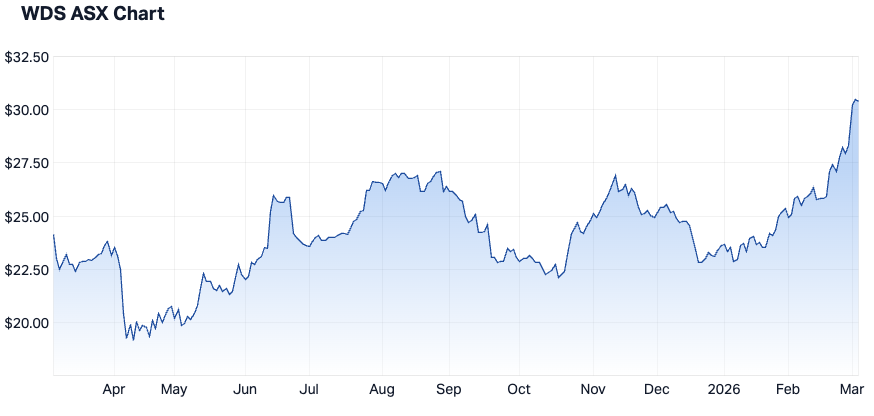
While Ord Minnett acknowledges that Woodside remains “an operationally sound business with quality management,” the unresolved CEO question, coupled with a softened outlook for the Liquefied Natural Gas (LNG) market and a strategic focus on free cash flow over immediate dividend payouts, has prompted this downward revision. Woodside has also faced downgrades from Morgans and Jarden, both of whom have moved from previous ‘Buy’-equivalent ratings to ‘Neutral’.
The Market Index’s Broker Consensus tool shows that out of nine tracked broker ratings, two are ‘Buy’, six are ‘Hold’, and one is a ‘Sell’. The consensus price target suggests a potential downside of approximately 11%.
AGL Energy Limited (ASX: AGL)
Morgan Stanley has downgraded AGL Energy Limited (ASX: AGL) from an ‘Equal-weight’ rating to ‘Underweight’, setting a price target of $9.66. This downgrade comes after AGL experienced a 10% rally following its solid first-half results, where profit declined by 5% but still managed to come in 9% ahead of estimates.
Morgan Stanley now considers AGL to be overvalued, with the price target suggesting a slight downside potential. In their analysis, Morgan Stanley pointed to potentially lower and less volatile electricity prices as a significant headwind for the company. This assessment was made prior to the recent escalation of conflict in the Middle East, which could introduce new market dynamics.
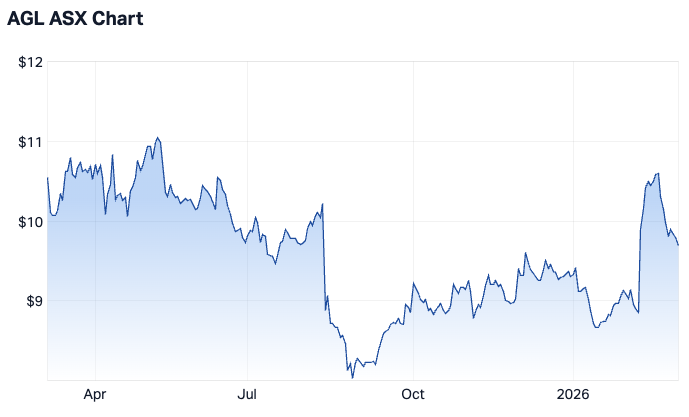
Despite Morgan Stanley’s bearish view, the consensus price target for AGL stands at $11.12, indicating a potential upside of about 13% from its current share price. Brokers like Citi and UBS maintain ‘Buy’ ratings, believing AGL is well-positioned for future earnings growth and net profit after tax (NPAT), respectively. Macquarie also holds a ‘Buy’ rating.
Interestingly, AGL still holds a ‘Buy’ rating on Market Index’s Broker Consensus tool. In a separate analysis on Livewire’s “Buy Hold Sell” program, Dushko Bajic of First Sentier Investors rated AGL a ‘Sell’, preferring Origin Energy instead. David Lloyd of Ausbil, however, rated AGL a ‘Hold’, citing better investment opportunities elsewhere. This divergence in expert opinion highlights the complex and often conflicting views surrounding the future prospects of these major energy companies.